

We’re captive on the carousel of time
We can’t return we can only look
Behind from where we came
And go round and round and round
In the circle game.
--Joni Mitchell, The Circle Game (1966)
With so much attention on energy affordability, many commentators are focusing on the process regulators use to set utility profit levels as a potential tool for reducing rates. Why does Duke Energy, for example — the utility with the highest profits in the United States — really need to make nearly $5 billion a year? Why can’t regulators simply reduce customer rates by cutting the profits utilities are allowed to earn?
This post will describe how regulators determine the level of profits in rate proceedings.
To the casual observer, the process will seem very circular – utilities base their rate requests on how much profits “comparable” utilities are allowed to earn. Regulators, in turn, tend to set returns that generally fall in line with what regulators in other states are allowing. Hence, the “circle game.” In fact, it is much more complicated.
Setting “Just and Reasonable” Rates
The ratemaking statutes in the vast majority of states require that regulators set rates that are “just and reasonable” or “fair, just, reasonable, and sufficient.” That translates into a ratemaking formula whereby a utility is allowed to collect revenue that recovers its operating expenses, as well as its capital costs, including a reasonable profit. The formula is generally stated as follows:
Utility Revenues = (Rate Base X Rate of Return) + Operating Expenses
A utility raises capital by issuing both debt and common stock (equity), so the Rate of Return component comprises both elements. The capital structure for electric utilities typically consists of approximately 50% to 60% equity and 40% to 50% debt. The relative proportion of debt and equity is frequently contested in rate proceedings, as the utility typically wants a higher equity ratio as a means of boosting the rate of return1. What is not a contested issue in rate proceedings is the cost of debt, which is simply the interest rate charged by the utility’s lenders, as evidenced by examining the utility’s various outstanding debt instruments (e.g., long- and short-term bonds).
The “action” in rate proceedings centers on estimating the cost of equity capital, or ROE. The goal for regulators in setting that allowed ROE is to reflect the utility’s actual cost of capital – in other words, the equity return that is necessary to compensate investors for the risk they are assuming and thereby enable the utility to attract capital on reasonable terms2. Given that the rate of return is multiplied by a utility rate base that typically runs into the billions of dollars, a few basis points higher or lower in the ROE can make a big difference in how much the utility is allowed to charge its customers. In other words, slashing a utility’s ROE can result in a much lower revenue requirement.
The Constitutional Underpinnings
In setting the allowed equity return, regulators are charged with balancing the interests of shareholders – who want a high level of profits on their investment – against the interests of customers, who want economical rates and protection from excessive profits. In striking that balance, the U.S. Constitution comes into play: the concept is that utilities (and their shareholders) are investing vast sums of money in the capital assets (e.g., in the case of an electric utility, transmission lines, and utility poles and wires) necessary to render utility service and, under the Fifth Amendment, they are entitled to “just compensation” on that investment. Two leading U.S. Supreme Court cases, Bluefield Water Works and Hope Natural Gas, provide guidance to regulators in setting that fair rate of return.
According to Bluefield Water Works, “[a] public utility is entitled to such rates as will permit it to earn a return on the value of the property which it employs for the convenience of the public equal to that generally being made at the same time and in the same general part of the country on investments in other business undertakings which are attended by corresponding risks and uncertainties . . .”3 Hope Natural Gas, decided 18 years later, states that “the return to the equity owner should be commensurate with returns on investments in other enterprises having corresponding risks. That return, moreover, should be sufficient to assure confidence in the financial integrity of the enterprise, so as to maintain its credit and to attract capital.4
This standard is based on the notion that utilities are competing with other entities in the debt and equity markets for access to capital and, to be successful in that competition, they must provide a return on that capital that compensates for the level of risk their investors are bearing. Hence, the reference to the returns earned on investments carrying similar risks.
The standard is sound in principle. In practice, it is the engine of the circle game.
Let the Circle Games Begin
From 1985 to 2007, I represented investor-owned utilities in the Northwest in rate proceedings, and was very much involved in helping the utility make its case for a high ROE, as well as challenging opposing testimony from consumer advocates and intervenors for a lower ROE.
Virtually every cost of capital witness will cite the Bluefield Water Works and Hope Natural Gas decisions in their testimony as the foundation for their assignment to help the regulator estimate the utility’s cost of equity capital. This is where the circle game comes into play.
In identifying investments in other enterprises having corresponding risks – the standard from Hope Natural Gas – witnesses will identify a group of utilities that arguably correspond to the risk of the subject electric utility. The cost of capital witness with whom I worked the most, for example, would start off with a universe of all the electric utilities that are included in the Value Line Investors Service (Value Line), which is a widely followed, reputable source of financial data. Then he would apply various “screens” to narrow that list to a group of “comparable companies” for purposes of comparison to the subject electric utility.
The most critical screen – and the one tied most directly to the Hope Natural Gas standard referring to corresponding risks – was based on the subject utility’s credit rating, more specifically its senior secured bond rating from the two primary rating agencies, Standard & Poor’s (S&P) and Moody’s. For an electric utility rated A- by S&P and A3 by Moody’s, for example, the group of companies would likely be narrowed to those with senior secured bond ratings of at least single-A by either S&P or by Moody’s.
Other screens would consider (1) the proportion of revenues derived from regulated utility sales (to roughly correspond to the risk profile of the subject utility in terms of exposure to competitive markets), (2) consistent financial records not affected by recent mergers or restructuring (utilities “in play” as possible merger targets will attract much higher prices and thus are not representative), and (3) a consistent dividend record (a utility recently cutting or reducing its dividend will depress its stock price in the short term).
This screening process would typically produce a comparable group of ten to fifteen companies to which the witness, in turn, would apply various cost of equity models5 to estimate the returns earned by each of the utilities in the selected group. The result arguably meets the Hope Natural Gas standard of the returns on investments in enterprises having corresponding risks. The testimony of other cost of capital witnesses tends to follow the same approach, but proposes a different group of comparable companies (e.g., a consumer advocate will usually select companies having lower risk, and thus resulting in a lower suggested return), and the dispute often turns on which set of companies is the most “comparable” to the subject utility.
The Outcome of the Circle Game
The problem is that if all the returns of the “comparable” utilities are too high, then the whole exercise results in the regulator correspondingly awarding an excessively high return for the subject utility. And thus we “go round and round and round in the circle game.” It’s a self-perpetuating cycle that, by its very nature, lacks a reality check.
Step 1. Utility A’s cost of capital witness selects a group of “comparable” utilities — all of which are already earning elevated ROEs — and uses their returns to justify a high ROE for Utility A.
Step 2. The regulator, believing that the process faithfully fulfills the constitutional standard, approves a return consistent with the returns earned by the utilities identified as “comparable.”
Step 3. Utility A’s approved ROE is now part of the dataset the next utility’s cost of capital witness will cite as a “comparable.”
Back to Step 1.
There is no external reference point. The circle is the methodology.
A Second Circle
It gets worse. Another reference point commonly cited in cost of capital testimony is the trend of allowed ROEs by regulators in other jurisdictions over recent historical periods. The point the witness tries to make to the regulator is that the recommended return is very much in line with what other regulators across the country have been allowing in recent cases. I can say from personal experience that regulators don’t like to be outliers, either high or low, in their decisions on equity returns. In other words, one objective is to avoid being flagged by equity analysts as being either too generous (on the upside) or a “hostile regulatory environment” (on the downside). Regulators tend to want to “move in packs” on equity returns, and cost of capital witnesses know that. As a result, they promote the consistency of their recommendations with recent ROE trends to provide regulators with some assurances that they will not be outliers. Two circles, moving together.
Customers Bear the Consequences
Recent analyses performed by cost of capital experts tend to show that allowed ROEs have been systematically set by regulators for decades at a level that far exceeds the actual cost of equity. For example, when I first started learning the utility regulatory business at the New York Public Service Commission in the 1980s, capital witnesses would typically recommend an ROE designed to achieve a market-to-book (M/B) ratio of 1.0. (The M/B ratio compares the utility’s stock price to utility shareholders’ investment, as reflected by the book value of equity record in the utility’s financial statements.) An M/B ratio of 1.0 suggests that allowed returns are in line with utilities’ actual cost of equity. From the late 1970s to the early 1990s – including the period when I was working for the NYPSC – the M/B ratio was less than 1.0, and striving to achieve an M/B ratio of 1.0 would thus generally support a higher allowed ROE. For the last 30 years, however, the M/B ratio has exceeded 1.0 and has drifted around 2.0 for the last 15 years, suggesting that utilities have been awarded ROEs approximately twice their actual cost of equity capital6. Financial experts using similar metrics have concluded that regulators are routinely granted equity returns far in excess of the actual cost of equity capital.7
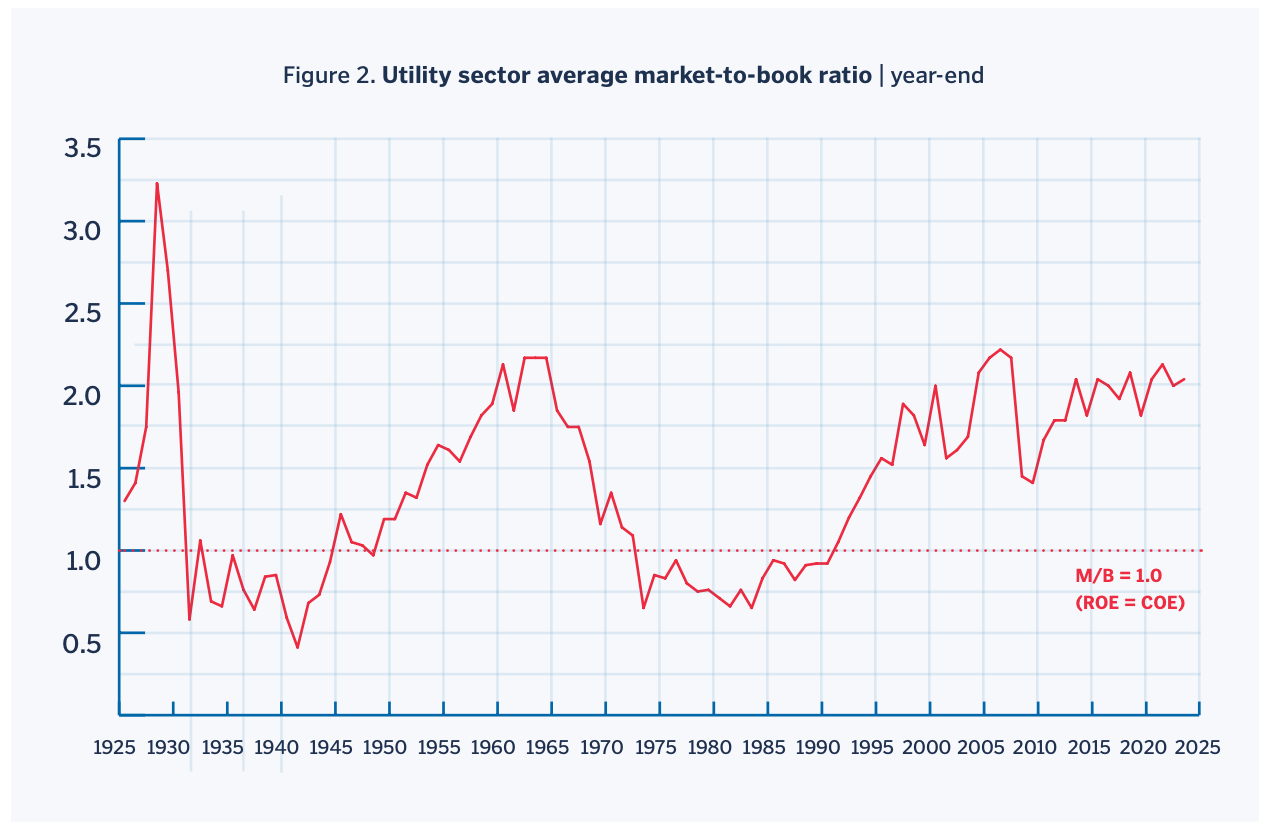
Source: Mark Ellis, “Rate of Return Equals Cost of Capital: A Simple, Fair Formula to Stop Investor-Owned Utilities From Overcharging the Public” (January 2025), Figure 2, p. 6.
As noted in my second Based Rates post, gas utilities have an incentive to over-invest in infrastructure as a means of increasing the rate base upon which they earn a return. Under rate-of-return regulation – as depicted in the ratemaking formula set forth above – operating expenses are merely a pass-through of costs incurred by the utility upon which it does not earn a return. The more an LDC spends on pipes, however, the more it earns. That incentive is even stronger when the regulator creates an “ROE gap” by setting a return on equity that exceeds the actual cost of equity. One analysis of this phenomenon concluded that a one percent increase in the ROE gap leads to a 3–4% percent increase in capital assets8. A downward adjustment to allowed returns to bring them in line with actual costs of equity would therefore not only reduce rates in the short term, it would also dampen the incentive to over-invest in infrastructure that leads to subsequent massive increases in the delivery charge portion of customers’ gas bills.
Where to Go From Here
As governors, legislators, and regulators in various states take a deeper dive into energy affordability and the tools available to hold utility rates down, the process regulators follow in setting utility equity returns needs to be high on the list of issues to explore. The level of profits is a major driver in determining the size of rate increases, and available analyses by qualified financial experts strongly suggest that profits are substantially higher than necessary to enable utilities to maintain financial integrity — and are ultimately contributing to over-investment in infrastructure.
The utilities and their consultants, of course, will defend the current process vigorously. They will argue that the comparable-company approach faithfully implements the constitutional standard from Bluefield Water Works and Hope Natural Gas standard and that regulators have reached these returns through reasoned, independent judgment. The circle game’s defenders have a ready answer for every criticism — which is precisely what makes it so durable. Breaking it requires regulators willing to act on what M/B data has been showing for three decades.
A future post will examine the issue of capital structure, which does not attract as much attention as the level of equity return but needs to be part of the discussion. There is some interplay between the ROE and the equity ratio in terms of the most economical solution for customers. A higher equity ratio (e.g., 55%), for example, could be coupled with a lower ROE. Utilities want both a high ROE and the thicker equity ratio, of course, and that is not economical for customers.
Keep in mind that the ratemaking process does not guarantee that utilities will actually earn the allowed ROE set by regulators; rates are set to provide the utility with a reasonable opportunity to earn that return. Actual earned returns are often lower than the ROE allowed by the regulator.
Bluefield Water Works & Improvement Company v. Public Service Commission of West Virginia, 262 U.S. 679, 692-693 (1923).Bluefield Water Works & Improvement Company v. Public Service Commission of West Virginia, 262 U.S. 679, 692-693 (1923).
Federal Power Commission v. Hope Natural Gas Co., 320 U.S. 591, 603 211 (1944).
The most common approaches to estimating the cost of equity capital are (1) discounted cash flow (DCF), (2) the capital asset pricing model (CAPM), and (3) risk premium. An explanation of these approaches is beyond the scope of this post.
Mark Ellis, Rate of Return Equals Cost of Capital: A Simple, Fair Formula to Stop Investor-Owned Utilities from Overcharging the Public, American Economic Liberties Project (January 2025), available at chrome-extension://efaidnbmnnnibpcajpcglclefindmkaj/https://www.economicliberties.us/wp-content/uploads/2025/01/20250102-aelp-ror-v5.pdf.
Karl Dunkle Werner and Stephen Jarvis, Rate of Return Regulation Revisited, Energy Institute as Haas (March 2025), available at chrome-extension://efaidnbmnnnibpcajpcglclefindmkaj/https://haas.berkeley.edu/wp-content/uploads/WP329.pdf;
Michael Lee, Performance-Based Regulation: The Incomplete Fix and What Should Come Next, Distributed Grid (Substack), March 2026, available at

.
Werner and Jarvis, supra note 6, at 6.
Nicely done. Agreed that the equity risk premiums seem substantially too high.
I'd also recommend citing the paper by David Rode and Paul Fischbeck, Regulated Equity Returns: A Puzzle in Energy Policy, Volume 133, October 2019.
Averch and Johnson, in their original 1968 paper, suggest a theoretical reason that the market-to-book ratio may exceed unity, which I believe Werner and Jarvis repeat. If the fair rate of return exceeds the cost of capital, a firm will have an incentive to invest as much as it can, consistent with its production possibilities, because the difference between the two represents pure profit. On the other hand, eliminating the gap may produce different and potentially problematic incentive structures.
I think assessing the subsidiary's equity risk is a substantial issue, particularly since debt risk likely varies across divisions as well. Consider a utility holding company with a regulated and an unregulated division. The regulated entity suppresses the company's overall debt risk. When using standard approaches to divisional equity risk, the fact that one division is regulated may not adequately account for the risk suppression that the regulated entity brings to the firm as a whole.